An HSA or FSA can usually pay for prescription GLP-1 treatment for a diagnosed condition such as obesity, but generally not cosmetic weight loss or ordinary over-the-counter diet products. For compounded products, get the administrator's acceptance decision in writing before paying, while remembering that payment approval doesn't establish tax eligibility.
The popular advice to “just use your HSA card” skips the most important work. Before the first prescription fill, you need a record of what condition the treatment addresses, what you're buying, and which charges your account can reimburse.
A pharmacy accepting your card isn't the same as an insurer covering your prescription. Building a small proof file before treatment starts can make those differences much easier to manage.
Which Weight-Loss Costs Your HSA or FSA Can Cover
Medical purpose is the starting point. Weight-loss care may qualify when it treats a diagnosed condition, while care purchased only to change appearance generally doesn't.
Use the following table as a screening tool, not an approval letter. Ask about each expense separately, especially when a program bundles medication, appointments, nutrition services, and other benefits into one payment.
HSA and FSA eligibility for common weight-loss expenses
| Expense | Typically Eligible? | Condition That Makes It Count | Practical Note |
|---|---|---|---|
| Prescription GLP-1 for diagnosed obesity, FDA-approved | Usually yes | Prescribed to treat a diagnosed condition | Keep the visit note and prescription label |
| Prescription GLP-1 for cosmetic goals only | Generally no | A cosmetic goal alone doesn't establish medical purpose | A prescription doesn't automatically make cosmetic treatment eligible |
| Compounded semaglutide or tirzepatide, not FDA-approved | Varies | Medical purpose and the administrator's acceptance requirements need review | Get an answer in writing before the first fill |
| OTC weight-loss pills or diet products | Generally no | Ordinary diet products don't automatically qualify as medical treatment | Ask about the exact product, not just whether it has a prescription |
| Telehealth visit fee for obesity care | Usually yes | The appointment provides medical care for a diagnosed condition | Keep the visit note and itemized charge |
| Lab tests monitoring obesity-related conditions | Often yes | Testing is ordered for medical evaluation or monitoring | Keep the lab order |
| Dietitian or medical nutrition therapy | Varies | Services address a diagnosed condition rather than general wellness | A letter of medical necessity may support review |
| Gym memberships | Generally no | General fitness alone doesn't establish eligibility | Don't assume a clinician's recommendation is enough |
| Meal replacement shakes or food | Generally no | Ordinary food purchases aren't automatically medical expenses | Any claimed exception needs specific review and documentation |
Usually and often describe a likely result when the medical and documentation requirements are met, not guaranteed approval. Varies means you should request an expense-specific review, while generally no means the ordinary purchase doesn't meet the medical-purpose test.
Ask about the charge, not just the program
A medical appointment and a meal-delivery subscription aren't interchangeable just because both support weight loss. If they appear on the same invoice, request separate descriptions and amounts rather than assuming the entire package qualifies.
HSA and FSA paperwork can also work differently. This explanation of whether FSA eligibility is the same as HSA eligibility can help you frame the right questions for your account.
Before committing, check the diagnosis, whether the actual medicine is FDA-approved, and whether the pharmacy accepts your account card. Those checks answer different questions, so keep the answers separate.
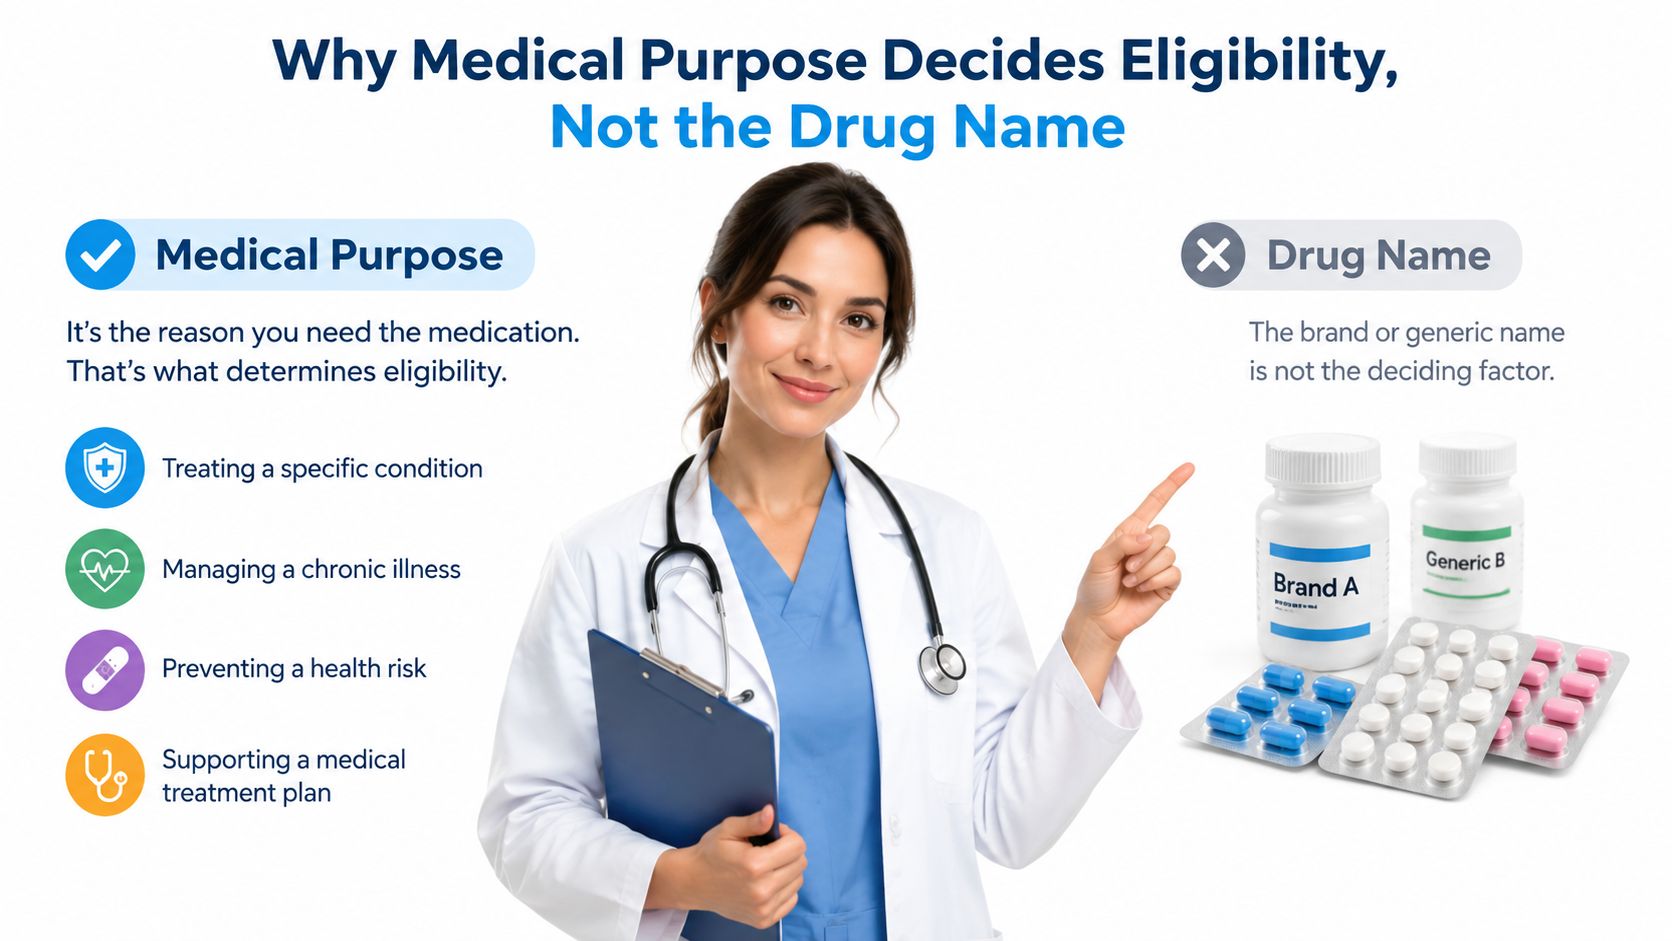
Why Medical Purpose Decides Eligibility, Not the Drug Name
A medication's name alone can't answer whether it qualifies for HSA payment. The deciding question is why it was prescribed and whether the medical purpose is documented. The same medicine may be used to treat a diagnosed condition or for appearance-related weight loss, and those uses can receive different treatment.
The drug is the tool; the diagnosis explains its medical purpose. That distinction helps you build a clear claim: connect the prescribed treatment to the condition it is intended to address. IRS Publication 502 and Revenue Ruling 2002-19 describe medical expenses in terms of their purpose. The medical-purpose distinction in HSA and FSA weight-loss guidance can help explain how that principle applies to weight-loss treatment. Cosmetic weight loss generally does not qualify.
An HSA pays for qualified medical expenses; it does not make an expense qualified.
Separate eligibility, coverage, and payment
An eligible expense meets the applicable medical-expense requirements. For weight-loss care tied to a disease, the records should show the connection between the treatment and the diagnosed condition.
Insurance coverage is a separate decision. KFF reported that in 2024, 1% of ACA Marketplace prescription drug plans covered Wegovy for weight loss, a finding about that specific indication, not all uses of the drug. See KFF's analysis of Marketplace drug coverage. A treatment may meet the medical-expense test even if an insurer does not cover it.
An HSA payment describes the source of the money, not whether the expense qualifies. A successful card transaction is not confirmation of medical eligibility or insurance coverage.
Understand who decides what
Your clinician determines whether treatment is appropriate and records the medical reasoning. Your insurer decides coverage under its policy. An FSA administrator reviews claims under the account's rules, while HSA account holders remain responsible for using funds for qualified expenses.
If an HSA payment is later found ineligible, ask the administrator about correction procedures and seek tax guidance. Do not treat payment approval as a binding tax ruling. A guide to GLP-1 treatment eligibility can help you prepare for the clinical discussion, but your clinician and account-specific review determine the relevant decisions.
Documents to Gather Before You Submit a Claim
Build your proof file while the appointment and pharmacy records are easy to retrieve. The aim is to connect the medical reason, the prescribed treatment, and the amount you paid.
Documents that prove a weight-loss expense qualifies
| Document | What It Proves | Where to Get It | Claims It Supports |
|---|---|---|---|
| Visit note with diagnosis | The condition being treated and the clinician's treatment plan | Provider after a video or in-person visit | Medication, visit, and lab claims |
| BMI record, including a Z68 code if recorded | The body mass index documented during assessment | Visit note or intake form | Obesity-based medication claims |
| Prescription label or record | Drug name, strength, quantity, and prescriber | Pharmacy label or patient portal | Medication claims |
| Itemized pharmacy receipt | Date, product, amount paid, and pharmacy | Pharmacy account or emailed receipt | Pharmacy claims |
| Explanation of benefits | How the insurer processed the charge and the stated patient responsibility | Insurer member portal | Claims where insurance was also billed |
| Letter of medical necessity | Why the provider considers the item necessary to treat a diagnosed condition | Provider, on request | Nutrition, product-specific, and borderline requests requiring review |
A receipt shows what you bought, but usually doesn't explain why it was prescribed. The visit note supplies that missing connection, while the prescription identifies the treatment.
An explanation of benefits serves another purpose: it helps separate the insurer's payment from your responsibility. Match it with the receipt rather than treating either document as a complete record on its own.
Make the file easy to review
- Match product descriptions. Check that the receipt and prescription label identify the same medicine. Ask the pharmacy to explain abbreviations or unclear product names.
- Use searchable filenames. Include the service date, provider or pharmacy, and document type when saving PDFs.
- Request chart documentation. Ask the provider to record the diagnosed condition and treatment rationale in the visit note, not only in a patient message.
- Keep the original record. Save the original receipt alongside any corrected or more detailed version.
- Ask before requesting extra letters. Find out whether the administrator needs a letter of medical necessity and what it must contain.
Paperwork check: If a reviewer opened your folder without speaking to you, could they connect the condition, treatment, and payment?
A letter can explain legitimate medical necessity, but it can't transform an otherwise ineligible purchase into an eligible one. Likewise, don't ask a provider to add a diagnosis that wasn't clinically established.
Keep records with the relevant tax and account documents, and confirm the applicable retention period with your administrator or tax adviser.
How to Get Reimbursed Step by Step
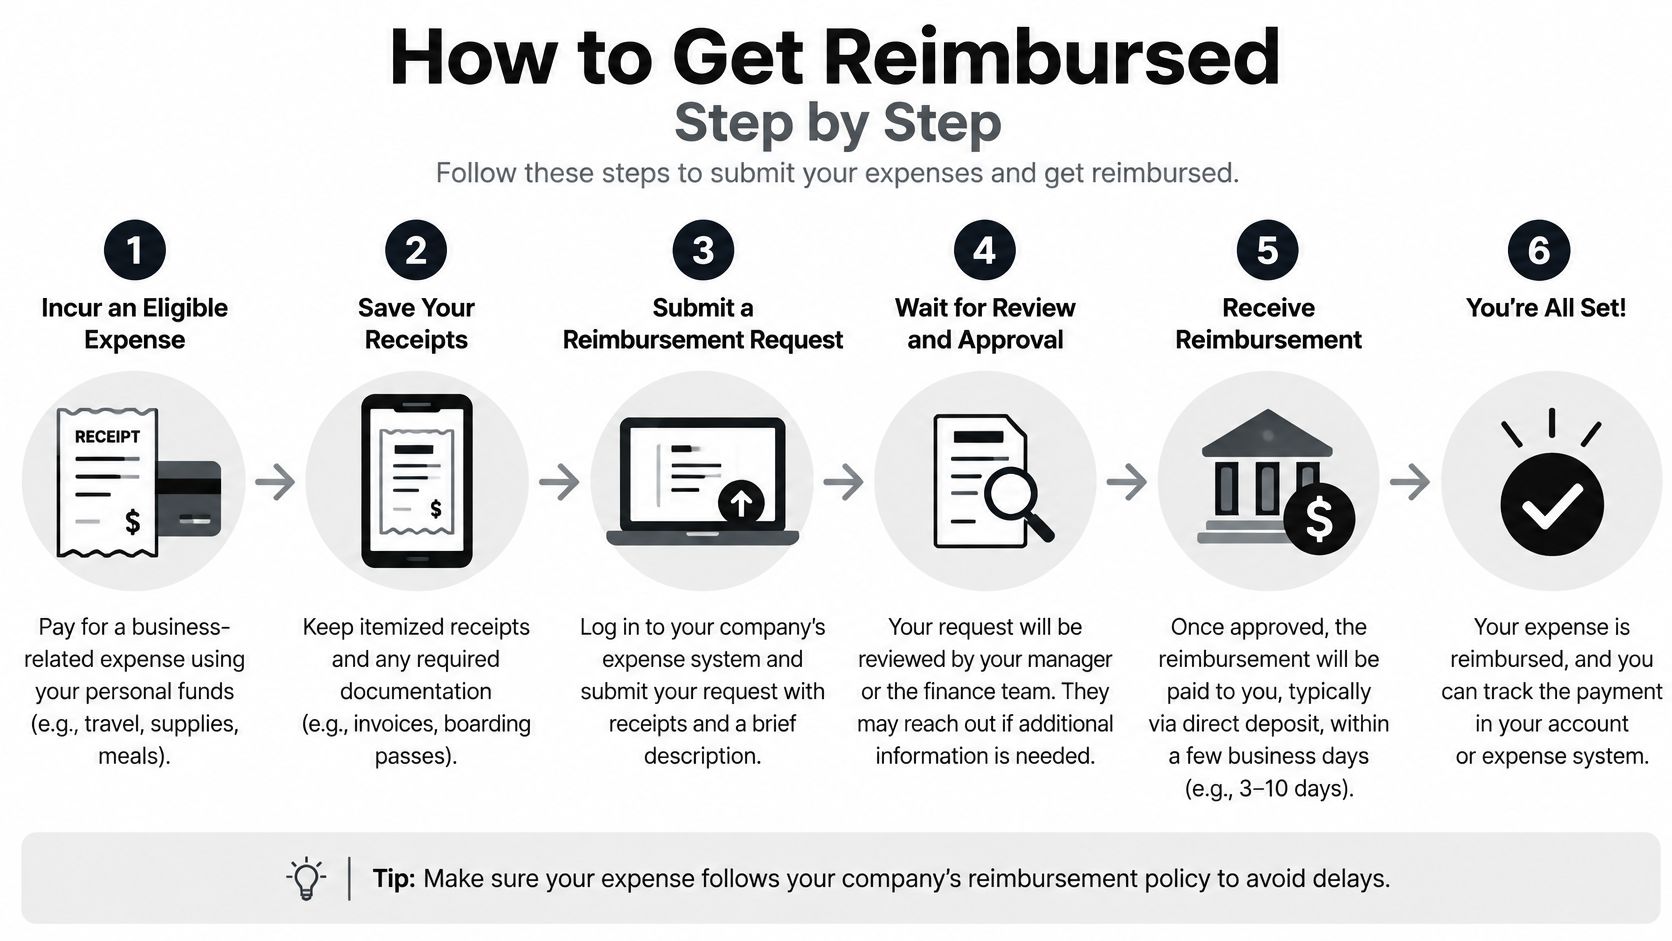
An eligible expense, insurance coverage, and the way you pay are three separate questions. An administrator decides whether a claim qualifies under the account's rules; an insurer decides what it covers; and the account's payment method determines how funds move. Confirm each before relying on reimbursement.
From payment to a complete reimbursement record
-
Identify your account and its process. Check your account documents instead of judging by the card's appearance. Ask whether you'll pay directly, submit a reimbursement claim, or pay personally and later request money from your HSA.
-
Confirm the expense before purchase. Review the diagnosis and prescription, then ask the administrator about uncertain charges. Check especially on compounded products or bundled program fees, since a prescription alone does not establish eligibility.
-
Pay the pharmacy or provider. Use an account card only if the merchant accepts it and you have checked the expense's eligibility. If you pay personally, save the payment confirmation so it can be matched to your later reimbursement request.
-
Collect the supporting documents. Keep the visit note, prescription label, and itemized receipt together. If insurance was billed, include the explanation of benefits and use it to calculate the amount you are requesting.
-
Enter the transaction in the correct portal. For an administrator-reviewed claim, choose the appropriate category and enter the service date, provider, and eligible amount. For HSA self-reimbursement, follow the custodian's process and keep your own records.
-
Upload clear files when required. Make sure each page is readable and corresponds to the expense in your claim. If the administrator requests a letter of medical necessity, provide it alongside the receipt, not in place of it.
-
Answer follow-up requests promptly. Note the administrator's deadline and respond to the specific request. A claim can remain unresolved if requested information is missing, even when you have other supporting records.
-
Reconcile and file the result. Confirm that an approved payment reached your bank account or that the HSA transfer was completed. Record which expense it covered to avoid requesting reimbursement for it again.
Plan for the payment gap
Paying first and receiving reimbursement later are separate events. Before paying out of pocket, consider whether you can cover the cost while the claim is reviewed. Approval and transfer timing may not match when you need the money.
Ask the HSA custodian about later reimbursement and any account-establishment requirements. For an FSA, confirm the eligible expense-incurrence window and the claim-submission deadline, including any grace period or run-out period that applies.
A grace period and a submission deadline serve different purposes. Ask the administrator which date determines when you must incur the expense and which date applies to submitting paperwork.
Claim Denials and How to Fix Them
A missing diagnosis is a practical place to start when a claim is rejected. If your receipt identifies only the medicine, the reviewer may need the visit note to understand the treatment's purpose.
Read the denial notice before uploading everything again. The useful question is whether the administrator needs missing evidence, a corrected amount, or an appeal of an eligibility decision.
Denial reasons, causes and fixes
| Denial Reason | Why It Happens | Fix |
|---|---|---|
| No diagnosis on file | The receipt shows the drug but not the condition | Request the visit note with the documented diagnosis and relevant diagnosis code |
| Cosmetic purpose | The request describes appearance goals only | If a genuine diagnosed condition was treated, submit the existing clinical documentation; don't relabel cosmetic care |
| Compounded product not accepted | The administrator's review rejects the non-FDA-approved product | Obtain the reason in writing and ask whether an appeal with medical-necessity documentation is permitted |
| Receipt missing product details | The receipt shows only a total or pharmacy name | Request an itemized pharmacy receipt |
| Already reimbursed by insurance | The requested amount overlaps with an insurer payment | Submit the explanation of benefits and request only the eligible unreimbursed portion |
| Service date outside plan year | The FSA expense falls outside the permitted window | Check the actual service date and plan provisions; correct a date error if one exists |
| Duplicate submission | The same charge was filed twice | Check claims history and withdraw or clarify the duplicate |
A deadline problem needs special care. If the expense truly falls outside the permitted period, a clearer receipt won't fix it, and changing the date isn't an acceptable solution.
Similarly, a medical-necessity letter isn't a universal override. Ask which rule the administrator applied and what evidence, if any, could change the decision.
Prevent avoidable repeat work
- Review claims regularly. A monthly routine can help you catch missing documents while the provider or pharmacy can still identify the transaction easily.
- Keep a calendar-year folder. Within it, separate receipts, clinical records, and reimbursement confirmations.
- Check claims history first. Before resubmitting, establish whether the original request is denied, pending, partially paid, or already completed.
Before an appeal: Ask for the specific reason, the applicable rule, and the evidence the reviewer would need to reconsider it.
Resubmit when the administrator requests a missing receipt or corrected detail. Consider an appeal when you disagree with the rule's application and can support your position with the required documentation.
Follow the appeal instructions and deadline in the notice. A focused explanation tied to the disputed requirement is more useful than sending a larger folder without context.
Telehealth Prescriptions and the Pre-Fill Decision
Consider Dana, an illustrative patient, not a reported case study, who has diagnosed obesity and high blood pressure. She prefers a video appointment because it fits around work, but she wants to understand the account rules before authorizing a prescription fill.
After her consultation, Dana asks for the visit note and the exact prescription details. She also requests an itemized explanation of the program's charges so she can distinguish medical appointments from medication and any other services.
Her most useful decision happens before payment: she sends the administrator the actual product and billing details, rather than asking whether “online weight loss” is covered.
Review the prescription and the invoice separately
Dana asks whether the prescription is for an FDA-approved product or a compounded preparation. She doesn't assume that recognizing the ingredient name establishes the approval status of the finished medicine.
She also separates the pharmacy's status from the product's status. A statement about an FDA-registered pharmacy doesn't, by itself, answer whether the dispensed product is FDA-approved.
For the account review, she asks whether the administrator needs separate medication and consultation receipts, whether any provider-related requirements apply, and what documentation is required for a recurring program charge. She saves the written response with her first invoice.
A guide to telehealth for weight loss can help you compare how remote care works. When comparing programs, ask how they deliver clinical follow-up and how they provide records for reimbursement, not merely whether they display an HSA or FSA label.
Budget for continuity, not just enrollment
Affordability matters beyond the first transaction. In a 2025 Cleveland Clinic analysis, people who continued treatment lost an average of 11.9% of body weight after one year, compared with 3.6% among those who discontinued early; more than 80% used lower maintenance doses, and discontinuation was commonly associated with cost, insurance problems, side effects, or shortages, as described in Cleveland Clinic's real-world treatment analysis.
Those findings aren't a prediction for Dana or any individual patient. They're a reason to discuss ongoing affordability and tolerability with the prescribing clinician before relying on advertised results.
An HSA can help with the payment burden, but it doesn't eliminate side effects, access interruptions, or the need for follow-up. Don't change doses or stop treatment solely to make an account balance last without discussing the situation with your clinician.
Complete the pre-fill check
- Confirm the account. Check whether you're using an HSA or FSA, the available balance, and the relevant account restrictions.
- Identify the exact product. Request written guidance for the prescribed medicine, including a separate answer for a compounded version.
- Obtain the clinical record. Make sure the visit note documents the condition being treated.
- Compare ongoing costs. Review the regular monthly charge, potential additional expenses, and the full treatment budget against available funds and applicable contribution limits.
- Set a claim calendar. Schedule document collection and reimbursement review around your FSA deadlines or HSA recordkeeping process.
Send the administrator a written question before the first fill: “For this prescribed product and these itemized services, what documentation do you require, which charges will you accept, and what deadlines apply?” Keep the response, then compare it with the program's actual invoice before paying.
Weight Method offers telehealth weight-management consultations and prescription treatment when clinically appropriate. Visit Weight Method to review its care options and ask how consultations and medication are billed, then confirm the specific expenses and documentation with your HSA or FSA administrator before enrolling.